How China Went From Fearing Western Automakers to Dominating the Global Auto Industry
A quarter-century after joining the World Trade Organization (WTO) in 2001, China transformed its automotive industry from one threatened by foreign competition into the world’s largest vehicle manufacturing powerhouse. A November 16, 2026, Fortune article by Mia Osmonbekov examined how China accomplished that remarkable reversal and why Western automakers are now struggling to compete.
Before joining the WTO, China protected its domestic automotive industry with tariffs as high as 100% and import quotas. Foreign automakers, including General Motors and Volkswagen, were already operating in China through joint ventures, but WTO membership required the country to lower trade barriers and expose domestic manufacturers to greater international competition.
At the time, Chinese policymakers feared foreign automakers would overwhelm local companies. The strategy was to require foreign manufacturers to establish joint ventures with Chinese partners, who would own at least 50% of the businesses. Foreign companies also faced local sourcing requirements, encouraging technology transfers and helping Chinese suppliers develop advanced manufacturing capabilities.
By the late 1990s, joint ventures accounted for more than 80% of China’s domestic vehicle production. Although the strategy helped establish a substantial manufacturing base, Chinese automakers initially struggled to develop vehicles capable of competing with established Western and Japanese brands.
China also encouraged domestic manufacturers to become less dependent on foreign automotive technology, offering tax incentives for research and development. In 2001, Beijing relaxed restrictions on new automakers to prepare the industry for increased competition. This helped create opportunities for companies such as BYD, which acquired an automotive manufacturing license in 2003, as well as Chery and Geely.
The biggest competitive breakthrough came with electric vehicles. European, Japanese, and American automakers had spent decades refining internal combustion engines, giving them a substantial technological advantage. China, however, already possessed a strong battery and electronics manufacturing industry, providing domestic companies with an opportunity to compete in a different segment of the automotive market.
China began supporting EV adoption in 2009 through programs deploying electric buses and taxis in cities nationwide. Early vehicles suffered from limited battery range and performance problems, but government procurement programs gave manufacturers opportunities to experiment, improve battery technology, and develop better products.
In 2015, Premier Li Keqiang announced the Made in China 2025 strategic initiative, establishing EV leadership as a national priority. Subsidies, preferential financing, research funding, and manufacturing investments helped Chinese automakers expand production and accelerate technological development.
Tesla’s arrival provided another important turning point. In 2018, China began relaxing foreign ownership restrictions for EV manufacturers, allowing Tesla to establish a Shanghai factory without a Chinese joint-venture partner. Construction began in 2019, and locally manufactured vehicles started reaching customers before the end of that year.
Tesla also sourced approximately 95% of its components locally, raising manufacturing standards throughout the supply chain.
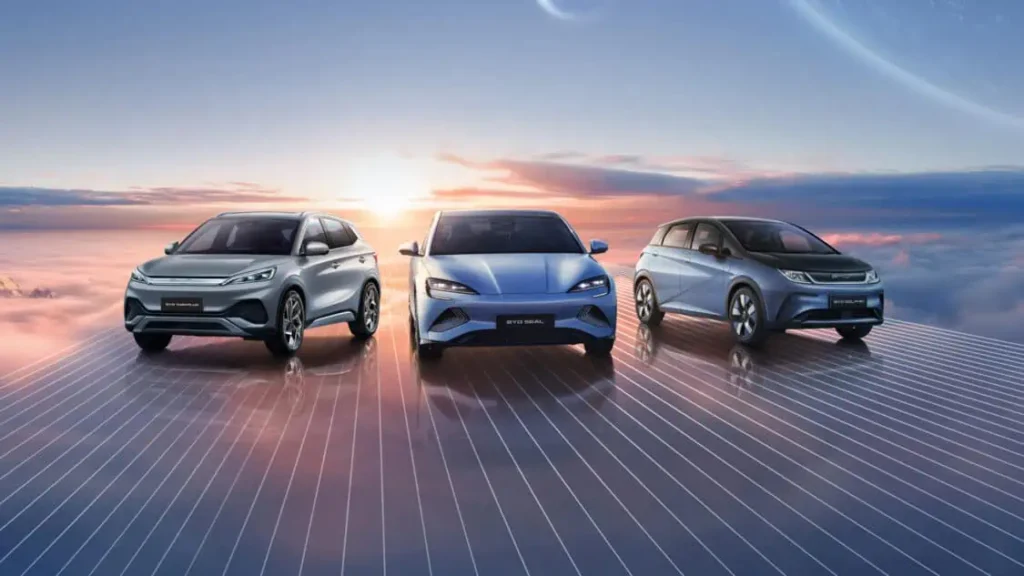
Chinese automakers subsequently entered an intense competitive environment characterized by rapid product development, aggressive pricing, and expanding production capacity. Companies including BYD, XPeng, and Xiaomi increased their international presence, gaining market share in Europe and Latin America.
However, China’s manufacturing expansion also created significant overcapacity. Domestic production exceeded consumer demand, contributing to aggressive price competition and forcing manufacturers to seek additional customers overseas. Chinese EV exports doubled to approximately 2.5 million vehicles last year, according to the article.
The rapid expansion prompted trade tensions. The United States raised tariffs on Chinese EVs to 100% in 2024, citing government subsidies and manufacturing overcapacity. The European Union also imposed tariffs on Chinese-made electric vehicles.
Meanwhile, established Western automakers face growing challenges in China. Volkswagen, which previously generated a substantial portion of its profits in the country, experienced declining deliveries as domestic manufacturers gained market share. Germany is even considering joint-venture requirements for foreign automakers, similar to the policies China implemented decades earlier.
China produced more than 7 million vehicles in the first quarter of 2026, compared with 3.7 million across the European Union and United Kingdom combined and 2.6 million in the United States. According to the International Organization of Motor Vehicle Manufacturers, China’s production was nearly twice that of the European markets combined.
The transformation illustrates how China leveraged foreign manufacturing expertise, domestic industrial policy, battery technology, and sustained investment to reshape the global automotive industry. Western automakers once entered China expecting to dominate its market. Today, many are struggling to compete against the manufacturers they helped develop.
EVinfo.net’s Take: U.S. EV Policy Blunders Raise Questions About America’s Ability to Compete With China
China’s automotive industry is rapidly expanding its global leadership in electric vehicles, batteries, and advanced manufacturing. Meanwhile, mistakes in changes to U.S. transportation and EV policies during 2025 and 2026 have altered the incentives and regulatory environment for domestic electrification.
The contrast raises an important question: How can American automakers compete with China’s increasingly sophisticated, cost-competitive EV manufacturers if the United States reduces support for electrification?
The federal government also ended new, used, and commercial clean-vehicle tax credits for vehicles acquired after September 30, 2025. Changes to clean-energy incentives and federal transportation policies have also worsened the investment environment for EVs and charging infrastructure.
The International Energy Agency reported that China accounted for nearly 75% of global electric car production and more than 80% of battery manufacturing capacity in 2025. Chinese automakers are benefiting from enormous production scale, integrated supply chains, battery expertise, and manufacturing costs estimated to be 35% lower than those in advanced economies.
For the United States to strengthen its competitive position, undoing bad federal policy enacted in 2025 and 2026 is key. Manufacturing investment, battery development, consumer incentives, charging infrastructure, and emissions standards deserve renewed attention. Reconsidering the 2025-2026 policy changes should be part of that discussion. Without a consistent long-term commitment to electrification, American automakers risk losing additional ground in the global automotive transition.
If current bad federal policies are allowed to stand, these policies will decimate America’s jobs and economic growth.
Electric Vehicle Marketing Consultant, Writer and Editor. Publisher EVinfo.net.
Services